OnePay – Mobile Banking
ONE Finance, Inc.FinanceVerified
- 17.49K Reviews
- 4.8
- Downloads
- 5,000,000+
- Price
- Free
Screenshots
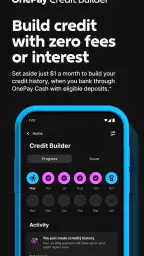
 Analysis by Appwesome
I approach OnePay – Mobile Banking as a finance app that needs to earn trust through clear choices, not just a tidy screen. It comes from ONE Finance, Inc., and its aim is to bring everyday money tasks into one mobile experience. That can be appealing if you want to handle payments and keep an eye on credit-building in the same place, but a finance app also deserves more scrutiny than a casual utility. I would decide whether it suits me by looking at what I need to do, what information I’m comfortable entering, and whether its account controls fit my habits.
OnePay is free, rated for Everyone, and has a 4.8 average from around 121,000 ratings. It has passed 5 million installs, so it is not an obscure experiment, though popularity alone should never be treated as proof that a financial tool is right for you. Its current version is 5.50.0, and it was released on July 23, 2020. Those details give useful context, but I would still judge the experience by the choices shown inside the app and the terms that apply to any financial products I decide to use.
Trust starts with the decisions you can inspect
Money apps often invite users to connect accounts, share personal details, or apply for products. Those are meaningful steps, not boxes to tap through automatically. I recommend pausing at each setup screen to read what is being requested and why, especially before linking another account or moving from basic app use into a credit-related flow. If the purpose is unclear, I would wait and review the relevant explanation rather than assume that every prompt is necessary for every user.
I also separate a polished interface from a verified security claim. The original article describes encryption and a quick support response, but I would not treat either as a substitute for checking the current privacy information, permissions, and account terms myself. What matters to me is whether the app explains its practices in language I understand and gives me a sensible way to manage access. I would avoid entering financial credentials on a device I do not control, and I would keep the phone itself protected with a screen lock.
Getting Started with OnePay
Setting up OnePay was a breeze. I downloaded the app from the Play Store, and within minutes, I was up and running. The interface is sleek and intuitive, making it super user-friendly even if you’re not tech-savvy. Signing up required just a few basic details, and I appreciated how the app guided me through the process with clear instructions.
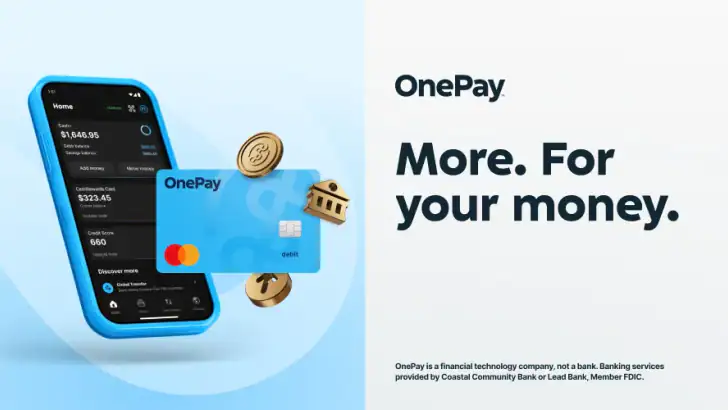
Once logged in, the dashboard showed me everything I needed at a glance. From checking my balance to viewing recent transactions, it’s all right there, and it’s as easy as pie. The app supports multiple banks, which is a huge plus if you juggle between different accounts.
Use it as a routine, not a shortcut
A useful way to test a financial app is to begin with one low-stakes routine rather than shifting every money task over at once. I would start by checking the dashboard and transaction history for a week, then compare what appears there with the statements from the accounts I already use. That simple cross-check helps me notice whether the view is complete enough for my needs before I rely on it to make a payment or judge my spending.
Other Stories to Read




For example, imagine I buy groceries after work, pay a utility bill later that evening, and then want to know why my balance changed. A combined view can make that review easier than opening several banking apps. I would still confirm a payment in the account or biller’s own records if timing matters, because a screen that is convenient for monitoring should not be mistaken for a guarantee about when a transaction will settle.
If you manage money with a partner or family member, I would also be deliberate about whose accounts are connected and which phone is used. A single dashboard can simplify your own overview, but it does not replace agreeing on who is responsible for a payment or how shared expenses are tracked. Keeping that distinction clear can prevent a handy view from turning into confusion about ownership or responsibility.
Features That Stand Out
One of the standout features of OnePay is its ability to transfer money seamlessly. I tried sending some cash to a friend, and it was fast and straightforward. No more fumbling around with account numbers and codes; it’s all done with a few taps.
Another feature I found incredibly handy is the bill payment option. Whether it’s utilities, credit card bills, or even topping up your mobile phone, OnePay has got you covered. Plus, you can schedule payments, which means no more missed deadlines or late fees. How cool is that?
Scheduling is most useful when it supports a routine you have already checked, not when it becomes a reason to stop reviewing bills. I would verify the amount, recipient, and intended date before scheduling, then leave enough time to notice any change to a recurring bill. For a first payment to a new recipient, a careful manual check is worth the small extra effort. That approach reduces the chance of carrying a typo or outdated amount into future payments.
Transfers and bill payments also have different consequences if something goes wrong. Before sending money, I would double-check the recipient details and confirm the amount on the final review screen. For a bill, I would compare the due date with the payment date and keep the biller’s confirmation until the payment appears where expected. These habits are useful with any finance app, but they matter especially when several actions sit close together in one interface.
For those who like keeping an eye on their spending habits, the app provides detailed expenditure reports. It categorizes your spending so you can see exactly where your money is going. I found this particularly useful because it helps me stick to my budget without the hassle of manually tracking expenses.
I would treat those categories as a helpful first draft, not as a perfect accounting system. A purchase can be classified in a way that does not match how I think about my budget, so the practical move is to inspect the underlying transactions before changing a spending plan. One non-obvious benefit of reviewing categories regularly is that it can reveal recurring charges I had stopped noticing. The report is more useful when I use it to ask a question—such as whether a weekly habit is adding up—rather than treating its labels as a verdict.
That makes the app a better fit for someone who wants a quick overview than for someone who needs detailed bookkeeping rules, custom reports, or a formal business ledger. A dedicated budgeting tool may offer more control over categories and planning, while a bank’s own app may be the clearer choice for account-specific details. I would use OnePay for convenience only if its summary lines up with the records I depend on.
Which everyday banking setup fits best?
Compared with using separate banking apps, the attraction here is having several everyday tasks gathered in one place. That can reduce the friction of checking balances, reviewing spending, and arranging payments. The trade-off is that an all-in-one view may not provide the same depth as each institution’s own app. If I need a detailed explanation of a particular transaction, a bank’s original statement or support channel remains the better source.
Compared with a spreadsheet or a standalone budget tracker, OnePay’s appeal is that the review and payment routines sit closer together. A spreadsheet can be more flexible and private in how I organize figures, but it relies on manual upkeep. A tracker can offer more deliberate budgeting tools, while OnePay may suit someone whose priority is handling common financial tasks without maintaining another system. I would not switch solely because an app combines functions; I would switch only if the combined workflow saves effort without obscuring the details I need.
The credit-building angle deserves a separate decision. I would first learn what product or process is involved, what obligations it creates, and what information is requested before starting. A person who only wants to pay bills may have no reason to explore that part. Someone actively trying to build credit may find the option relevant, but should compare the applicable terms with alternatives and avoid assuming that an app’s broad purpose guarantees a particular credit outcome.
Security and Support
Now, let’s talk about security because, let’s face it, with mobile banking, security is everything. OnePay uses top-notch encryption technology to ensure your data stays private and secure. I felt pretty confident knowing my financial information was in safe hands.
If you ever run into any issues, their customer support is just a tap away. I had a minor query and was impressed by how quickly they got back to me with a solution. It’s always reassuring to know help is available when you need it.
For my own trust check, I would look at the permissions the app requests on my device and ask whether each one makes sense for the task I am trying to perform. I would also review the app’s privacy information before connecting financial accounts, and revisit those choices if my needs change. Permissions and data choices are not one-and-done decisions: a user can be comfortable with one feature while choosing not to use another that asks for more access or personal information.
I would keep a separate record of important payment confirmations while learning the app, and check the relevant account if a transaction looks delayed or unfamiliar. If I saw an unexpected transaction, I would use the available account controls and contact the appropriate support channel promptly rather than relying on a general spending chart to explain it. This is a cautious workflow, not a claim that a specific control is available in every circumstance; the options shown in the app and the terms for the account should guide the next step.
That is also why the support experience matters, but I would not make a major financial decision based only on a quick reply to a minor question. For account access, a disputed transaction, or a product term I do not understand, I would want a clear answer tied to the specific issue. Before depending on any app for a deadline-sensitive payment, I would learn where its help options are and keep the biller’s own contact route available too.
Who should keep looking?
I can see this being useful for people who want a single mobile place to check money activity and manage routine payments, especially if they are comfortable reviewing their transactions regularly. It may also suit someone who wants to explore credit-building as part of a broader finance routine, provided they read the conditions before proceeding. The free price makes trying the basic experience less of a commitment, but it does not remove the need to understand any separate financial product terms.
I would steer away if you need advanced budgeting controls, depend on a particular bank’s detailed tools, or do not want to connect financial accounts to another service. It is also not a good fit for someone who prefers handling sensitive tasks only through a branch or their existing institution’s own app. There is no benefit in consolidating everything if doing so makes you less comfortable or less certain about where a transaction is recorded.
Before making OnePay part of a regular routine, I would answer a few practical questions for myself: Can I find the account and payment information I actually use? Do I understand what I am agreeing to when I connect an account or explore credit features? Can I verify scheduled payments and resolve a problem without guessing? If any answer is no, I would keep the app limited to low-stakes browsing or stick with my current provider until I have clarity.
A cautious verdict
All in all, I’ve been genuinely impressed with OnePay – Mobile Banking. It’s practical, reliable, and makes managing your finances a whole lot easier. Whether you’re a newbie to mobile banking or a seasoned pro, this app has something to offer. It’s like having a bank in your pocket, minus the long queues and complicated processes.
If you’re looking to streamline your financial tasks, give OnePay a shot. You might just find it’s the banking solution you’ve been waiting for.
My recommendation is to try it in stages: get familiar with the layout, check whether the account overview matches your existing records, and only then consider relying on it for routine payments. Keep your existing bank’s app available for details the consolidated view does not answer, and take time to inspect the terms and data choices before using any credit-related option. That measured approach lets the convenience prove itself without asking you to trust more than you have actually checked.
Highlights
- Intuitive user interface for easy navigation.
- Supports multiple bank accounts seamlessly.
- Real-time transaction notifications.
- Secure login with biometric authentication.
- Low transaction fees compared to competitors.
Limitations
- Limited customer support availability.
- Occasional app crashes reported by users.
- Some features require a premium subscription.
- International transfers can take longer.
- Limited integration with third-party services.
Frequently Asked Questions
01What is OnePay and how does it work?
OnePay is a mobile banking app designed to simplify financial management by offering a range of services such as money transfers, bill payments, and account management directly from your smartphone. Users can link their bank accounts, track transactions, and manage finances all in one place, providing a seamless banking experience.
02Is OnePay secure to use for my financial transactions?
Yes, OnePay prioritizes user security by implementing advanced encryption technologies to protect financial data. The app includes multi-factor authentication and biometric login options, ensuring that only authorized users can access their accounts. Regular security updates further enhance the app's protection against potential threats.
03What features does OnePay offer to its users?
OnePay offers a variety of features, including real-time balance updates, transaction history, and the ability to transfer money to other bank accounts. Users can also pay bills, set up recurring payments, and receive notifications for important account activities, making it a comprehensive tool for managing daily finances.
04Can I use OnePay if I have accounts with multiple banks?
Absolutely, OnePay is designed to work with multiple bank accounts, allowing users to link and manage all their finances from one app. This feature provides a consolidated view of your financial situation and facilitates easy transfers and payments across different banks, enhancing convenience and efficiency.
05Are there any fees associated with using OnePay?
While OnePay itself may be free to download and use, certain features like international money transfers or expedited payments might incur fees. It's important to review the app's terms and conditions and consult with your bank to understand any potential charges that may apply when using specific services within the app.


